If the rules were already in place, how did the banking industry get here?

By Omar F M’Bai
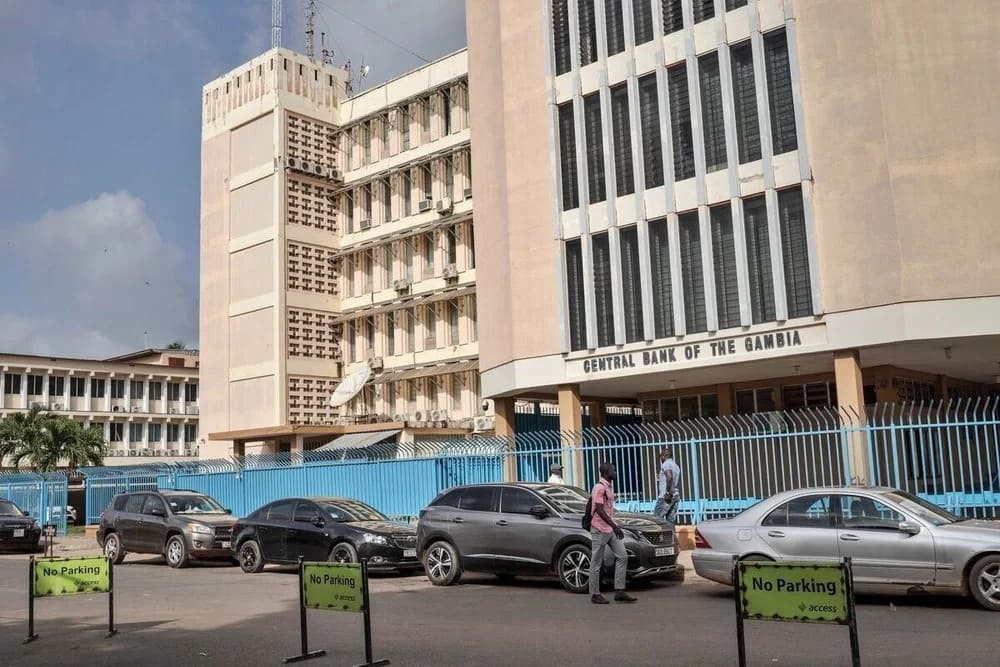
The recent directive of the Central Bank of The Gambia requiring commercial banks to phase out certain non-Gambian employees and replace them with suitably qualified Gambian nationals raises an important issue that goes beyond expatriate employment. It raises a broader question of regulatory accountability.
There should be little controversy over the principle that Gambian laws must be obeyed, that Gambians should be afforded meaningful opportunities within their own economy, and that expatriate employment should not become a substitute for developing competent local talent. Equally, where specialised skills are genuinely unavailable locally, a modern economy must remain capable of attracting expertise while ensuring structured knowledge transfer.
The real question, therefore, is not whether commercial banks should comply with the law. They must.
The more difficult question is this that if the rules governing expatriate employment in banks have existed for years, if expatriate numbers are expressly regulated, if certain appointments require Central Bank approval, and if banks operate under continuing regulatory supervision, how did the banking industry arrive at a situation sufficiently serious to warrant a sector-wide directive in September 2026?
That is not an accusation. It is a legitimate governance question.
In its letter dated 16th September 2026, addressed to managing directors of all banks, the Central Bank stated that an industry study had revealed that a “relatively high number of non-Gambians” were employed by banks “in addition to recognised expatriate staff.” It characterised the situation as contrary to the Labour Act 2023 and inconsistent with Guideline 9 on expatriate staff. Banks were consequently directed to replace affected non-Gambian staff with suitably qualified Gambians, with appropriate arrangements for skills transfer and continuity of operations, by 31st December 2026.
On its face, the directive pursues an entirely legitimate objective which is compliance with Gambian law and the development of Gambian participation in the banking industry. But reading the directive together with the Central Bank’s own regulatory framework produces questions that deserve careful consideration.
The restriction on expatriate staffing within commercial banks did not begin in September 2026. The Central Bank’s published Management and Technical Services Agreement Guidelines issued under Section 71(3) of the Banking Act 2009 contain specific provisions dealing with senior management and expatriate staff. Senior managers include the managing director, executive director, general manager, financial controller, company secretary and persons regarded as occupying positions of influence.
For the avoidance of doubt, Section 71 titled “Regulations, guidelines and orders by the Bank.” Section 71(3) provides:
“(3) The Bank may:
(a) issue such guidelines, interpretation bulletins or other regulatory statements as the Bank may consider necessary or desirable for the administration of this Act and the regulations and
(b) prescribe penalties for violation of the guidelines, interpretation bulletins or other regulatory statements by persons who have received written notice of them from the Bank.”
“Paragraph 9.0 of the CBG’s Management and Technical Services Agreement Guidelines commonly identified within the supervisory framework as Guideline 9, provides that expatriate staff shall be limited to three (3), save where a newly established subsidiary obtains special dispensation from the CBG and provides an acceptable plan to recruit and train local staff to take over from the expatriates.”
That is significant. The regulatory architecture did not simply express localisation as an aspiration. It imposed a limit, contemplated exceptions requiring regulatory approval, and connected those exceptions with the development and eventual succession of Gambian personnel.
The same regulatory framework also subjects relevant management arrangements to Central Bank oversight and makes renewal of certain senior appointments subject to approval. The natural question therefore becomes if present staffing arrangements were inconsistent with these longstanding requirements, when did the inconsistency arise, and through what weakness in the regulatory or compliance process was it able to persist?
The position becomes clearer still when Guideline 13 on Corporate Governance for Commercial Banks is considered. It expressly links expatriates in Senior Management to the requirements of Guideline 9. It also requires certain senior positions to be occupied by Gambian nationals and requires banks to maintain a well-documented and robust succession plan for Senior Management.
So, read together, Guideline 13 does four important things:
1. It expressly incorporates Guideline 9 into the Corporate Governance regime for expatriates in Senior Management.
2. It requires either the MD/CEO or DMD or, where there is no DMD, the next most senior officer to be Gambian.
3. It makes compliance with Guideline 9 a condition of Senior Management appointments.
4. It requires banks to have a robust succession plan, which is directly consistent with the policy of developing Gambians to take over senior roles.
These provisions demonstrate that localisation, succession planning and the regulation of expatriate participation at senior levels were already embedded within the corporate-governance framework of Gambian banking. The September 2026 directive therefore appears, from its own language, not merely to introduce a new expectation but to address perceived non-compliance with an existing regime.
This distinction is therefore critical to the analysis.
The Banking Act 2009 adds another important dimension. Banking institutions are required to obtain Central Bank approval before appointing persons to Senior Management, and directors are similarly subject to regulatory approval.
It would therefore be inaccurate to suggest that the Central Bank approves every foreign employee working in a commercial bank. It does not. Its role, however, becomes much more direct where the person concerned occupies Senior Management or another regulated position.
That distinction should be central to any discussion of the present directive.
If the non-Gambian employees identified by the CBG’s study were predominantly junior, technical or operational staff falling outside the Central Bank’s appointment-approval framework, responsibility for their immigration, labour and expatriate-quota status may principally lie elsewhere.
But if a material number occupied Senior Management or other positions for which regulatory approval was necessary, more difficult questions arise.
Were those appointments approved?
If they were not, how did persons requiring regulatory approval occupy those positions?
If they were approved, on what basis are their appointments now considered inconsistent with the applicable expatriate requirements?
And if the regulatory position or interpretation has since changed, should the transition from one position to another not be clearly explained?
These are questions about institutional process, not personalities.
Fairness also requires recognition that the Central Bank is not the only institution responsible for regulating expatriate employment in The Gambia. Section 30 of the Labour Act 2023 (Part V) establishes an Expatriate Quota Allocation Board with responsibility for considering quota applications, advising the responsible Minister and monitoring implementation. The Act also provides for monitoring and enforcement arrangements involving public institutions charged with inspecting establishments employing non-Gambians.
The legislation further requires an employer granted an expatriate quota to employ a Gambian counterpart capable of understudying the expatriate, thereby facilitating the transfer of knowledge and skills. The statutory framework also discourages the granting of expatriate quotas where the necessary knowledge, skills or expertise are available locally.
The point is therefore not that The Gambia lacks a legal or regulatory framework.
Quite the opposite. There are rules. There are approval mechanisms. There are monitoring responsibilities. There are succession and understudy requirements. There are inspection powers. And there are sanctions for non-compliance. That is precisely why the present situation calls for careful institutional examination.
A sound regulatory response should not end with identifying the immediate breach. It should also seek to understand how the control environment permitted that breach to arise.
Banks operate within an intensive supervisory environment. Organisational structures, senior-management changes, governance arrangements and other prudential information are ordinarily matters of interest to banking supervisors. Where shortcomings are detected, the supervisory process exists precisely to require remedial action.
If the CBG’s recent study uncovered isolated cases of non-compliance, the explanation may be relatively straightforward in that particular institutions failed to comply and enforcement followed.
But the language of the September directive suggests something broader. It was issued to all banks following an industry study and referred to a relatively high number of non-Gambian employees.
That reasonably raises another question. Was this a recent development, or was it a longstanding practice that had not previously been identified, challenged or effectively corrected?
If it was longstanding, it would be useful to know whether earlier supervisory examinations identified the issue, whether dispensations had been granted, whether commercial banks and regulators were applying different classifications to certain categories of foreign staff, whether the information available to the CBG differed from the records maintained by the institutions administering expatriate quotas, or whether there were weaknesses in regulatory coordination.
None of those possibilities should be assumed. But neither should they be excluded from proper examination.
Perhaps one of the most interesting expressions in the CBG’s own directive is the reference to non-Gambians employed “in addition to recognised expatriate staff.”
The wording appears to contemplate a distinction between “recognised expatriate staff” and other non-Gambian employees.
That distinction deserves clarification. If the CBG’s applicable guideline treats expatriate status broadly, what precisely is the legal or regulatory category occupied by these additional non-Gambian employees?
Were they foreign employees who did not qualify as recognised expatriates for regulatory purposes? Were they persons with labour quota approvals but falling outside the recognised CBG expatriate complement? Were they secondees, technical staff or employees occupying some other lawful category? Or were they employees whose engagements simply did not comply with applicable requirements?
The answers matter because regulatory enforcement should proceed on clearly understood legal classifications, rather than nationality alone.
There is another question that may prove equally important what happens to approvals that were validly granted before the directive?
Neither the Labour Act nor the banking regulatory framework appears to impose an absolute prohibition upon the employment of foreign nationals. Both contemplate circumstances in which expatriate expertise may legitimately be required, provided that the relevant approvals, limitations and localisation obligations are satisfied.
The September directive, however, uses broad language requiring banks to replace existing non-Gambian staff.
It would therefore be useful to clarify whether the directive is aimed exclusively at employees whose appointments are already non-compliant or whether it is intended to extend to individuals who presently hold valid expatriate quota clearances and, where relevant, valid Central Bank approvals.
If valid approvals exist, their treatment becomes important.
Regulatory certainty is itself an element of sound governance. Institutions should understand whether they are being required to remedy an existing breach or whether they are being required to adjust to a newly adopted regulatory position.
Those are materially different propositions.
None of this absolves the commercial banks of responsibility. If banks exceeded applicable expatriate limits, failed to obtain required quota clearances, improperly classified employees, failed to provide Gambian understudies, disregarded succession requirements or appointed regulated persons without the necessary approvals, those matters should be addressed in accordance with the law.
But regulatory accountability should not operate in only one direction.
A regulator is strengthened, rather than weakened, when it is prepared not merely to identify shortcomings within regulated institutions but also to examine whether its own approval, reporting, monitoring, supervisory and inter-agency coordination processes functioned as intended.
That is not an attack upon regulatory authority. It is an affirmation of good regulatory governance.
Indeed, where a problem appears sufficiently widespread to require intervention across an entire regulated industry, regulatory introspection becomes particularly valuable.
The proper question, therefore, is not simply Why is the Central Bank doing this?
The policy objective of ensuring compliance with Gambian law and developing Gambian professionals is readily understandable.
The deeper question is: If the Central Bank is now enforcing requirements that have long existed, what does the present exercise tell us about the effectiveness of the supervisory and approval framework that preceded it?
The current exercise provides an opportunity for something constructive. Without disclosing confidential information concerning individual institutions or employees, the Central Bank could clarify the nature of the findings that prompted its intervention, explain the distinction between recognised expatriates and other non-Gambian employees, indicate the treatment of existing lawful approvals, and outline how the CBG intends to coordinate with those public institutions responsible for administering expatriate quotas under the Labour Act.
Such transparency could benefit all concerned. It could reassure Gambian professionals that localisation is being implemented through a principled and sustainable framework. It could provide regulated institutions with greater certainty. It could distinguish genuinely lawful expatriate employment from non-compliant employment. And it could demonstrate that the purpose of regulation is not simply to remedy past failures but to understand why they arose and prevent their recurrence.
There is every justification for The Gambia to develop Gambians capable of leading and operating its financial institutions. The banking industry should not indefinitely depend upon imported expertise where competent Gambian talent exists or can reasonably be developed. The statutory emphasis upon understudies, knowledge transfer and succession planning reflects an understandable national objective.
But sustainable localisation requires more than a deadline. It requires planning, predictability, effective supervision, coordination between responsible institutions and a regulatory environment capable of distinguishing genuine skills needs from avoidable dependence on expatriate labour.
The Central Bank’s September directive therefore poses two legitimate questions. The first is for the commercial banks.
Have you complied with the expatriate, localisation, succession and regulatory approval requirements applicable to your institution?
The second is for the wider regulatory architecture.
If those requirements were being breached on a sufficiently broad scale to require an industry-wide directive, how did the existing approval, monitoring and supervisory systems permit that situation to develop?
A mature regulatory system should be capable of asking both questions simultaneously. The Central Bank should enforce compliance firmly wherever breaches are established, but that enforcement is strengthened, not diminished, when the regulator is equally willing to examine whether its own approval, monitoring, supervisory and inter-agency coordination processes functioned as they should. Regulatory authority is most credible when it is accompanied by institutional self-examination, particularly where a problem appears sufficiently widespread to require intervention across an entire industry.
Ultimately, therefore, this is not merely about correcting a breach by 31st December 2026. It is about ensuring that, from 1st January 2027 onwards, The Gambia has a clearer, more coherent and more effective regulatory framework capable of preventing the same problem from quietly developing again. That is the difference between correcting a breach and strengthening a regulatory system.
And that leaves one final, unavoidable question of institutional accountability: Who regulates the regulator?
Omar FaFa M’Bai is a legal practitioner, a governance advocate, and a parent based in Dubai, UAE. He writes regularly on institutional integrity, leadership, and education across Africa, Middle East, and Asia.